
Is a cracked windshield worth the risk of a higher monthly premium? Many drivers choose to ignore glass damage because they fear the hidden costs in their policy's fine print. You're likely asking, does a glass claim raise my insurance rates? In most cases, these incidents are viewed as no-fault events that don't trigger the same penalties as a standard collision. Understanding how your provider views glass repairs is the first step toward making a smart financial decision for your vehicle.
It's stressful to weigh the cost of a deductible against the potential for rising rates. We'll help you navigate this uncertainty by explaining how insurance claims work in 2026. This guide covers the impact of advanced technology like ADAS recalibration on claim values and provides a framework for deciding when to use your coverage. You'll gain a clear understanding of the risks to your premium and the best way to handle your glass repair with confidence. We'll show you exactly how to evaluate your options before you call your agent.
Key Takeaways
- Learn why the answer to "does a glass claim raise my insurance rates" is usually no, as most providers categorize glass damage as a no-fault comprehensive event.
- Understand the difference between comprehensive and collision coverage to see why glass repairs rarely signal driver risk to your insurer.
- Discover how many insurance policies waive deductibles for windshield repairs to encourage proactive maintenance over full replacements.
- Use our decision framework to compare your deductible against repair costs to determine if filing a claim is the right financial move.
- See how professional ADAS recalibration ensures vehicle safety and why this essential service is typically covered under your existing glass policy.
The Short Answer: How Glass Claims Affect Your Premiums
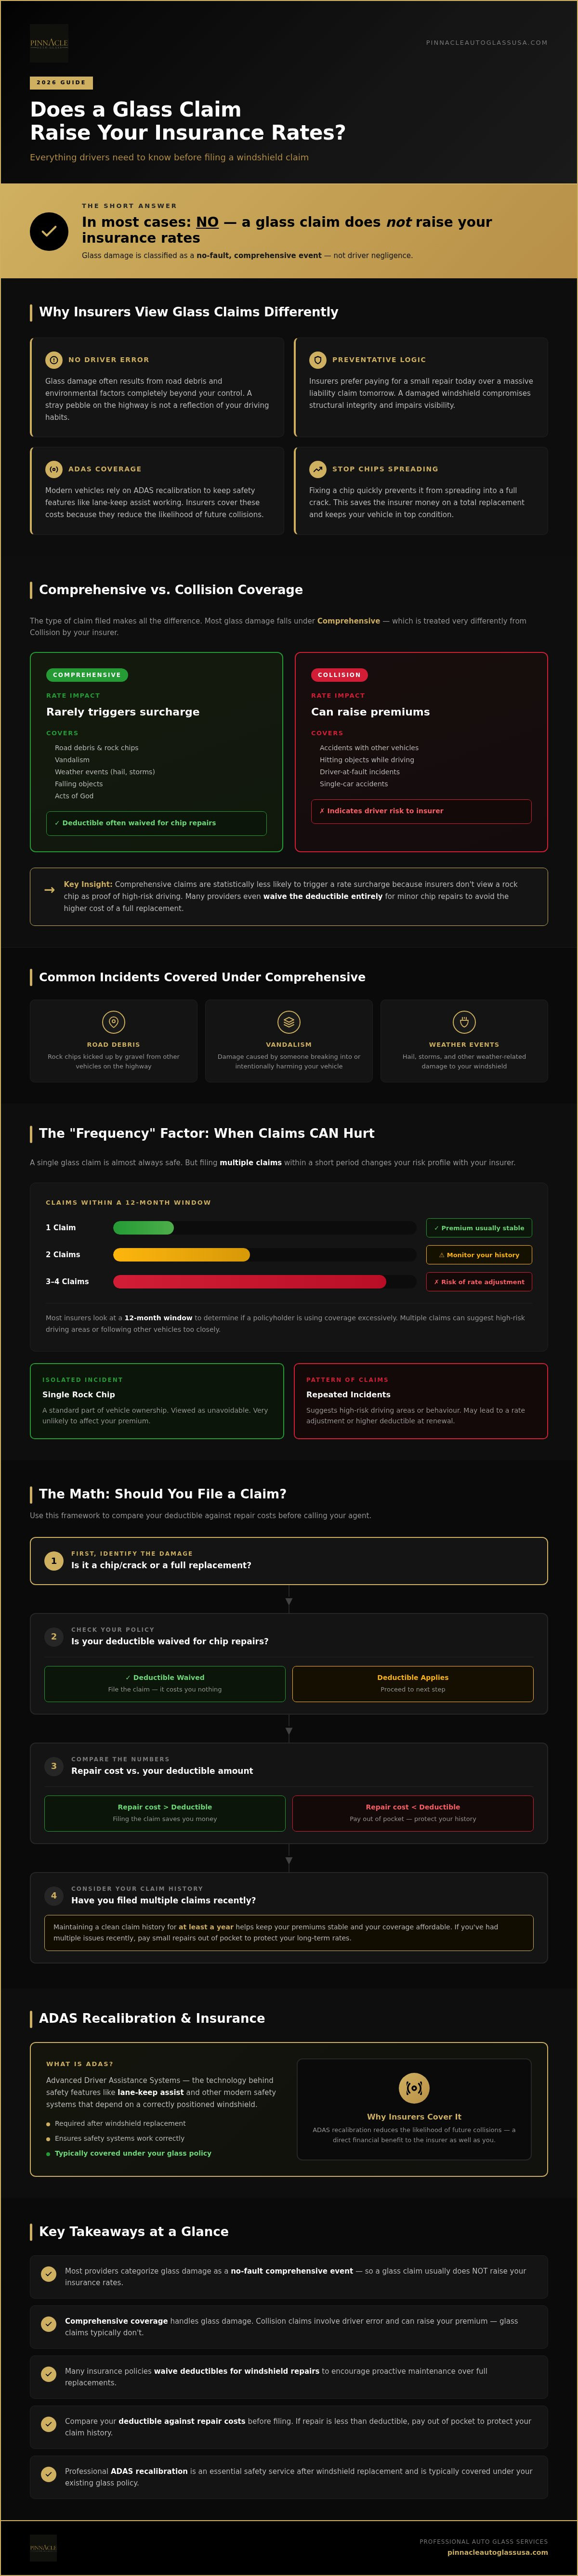
The most common question vehicle owners ask after a rock chip appears is, does a glass claim raise my insurance rates? For the vast majority of drivers, the answer is no. Insurance providers categorize glass damage as a non-collision event that is typically covered under the comprehensive portion of your policy. A glass claim is a non-collision event that insurers view as low-risk because it doesn't indicate poor driving behavior. Because these incidents don't involve driver error or negligence, insurers rarely use them as a reason to justify a premium hike.
Most glass damage results from road debris or environmental factors beyond your control. These are classified as no-fault incidents. When a stray pebble hits your windshield on the highway, it isn't a reflection of your driving habits. Consequently, filing a single claim for a windshield repair or replacement rarely impacts your monthly costs. Insurers prioritize keeping your vehicle safe and roadworthy over penalizing you for bad luck on the road. They understand that a clear view of the road is essential for accident prevention.
Why Insurance Companies View Glass Differently
Car insurance companies distinguish between a fender bender and a cracked windshield for several reasons. First, glass damage is often unavoidable. Even the most cautious drivers can't dodge every piece of gravel. Second, insurers would rather pay for a small repair today than a massive liability claim tomorrow. A damaged windshield compromises the structural integrity of your car and can impair your visibility, leading to much more expensive accidents. Keeping your safety ratings high is a priority for both you and your provider.
- Safety Systems: Modern vehicles rely on ADAS recalibration to ensure safety features like lane-keep assist work correctly. Insurers cover these costs because they reduce the likelihood of future collisions.
- Preventative Care: Fixing a chip quickly prevents it from spreading into a full crack. This saves the insurer money on a total replacement and keeps your vehicle in top condition.
The 'Frequency' Factor in Rate Adjustments
While a single claim is usually safe, your risk profile changes if you file multiple claims within a short period. Most insurers look at a 12-month window to determine if a policyholder is using their coverage excessively. If you file three or four glass claims in one year, the company might view you as a higher risk. This could potentially lead to a rate adjustment or a higher deductible when your policy renews.
It's important to differentiate between an isolated incident and a pattern of claims. An isolated rock chip is a standard part of vehicle ownership. However, a pattern of frequent claims suggests you might be driving in high-risk areas or following other vehicles too closely. Maintaining a clean claim history for at least a year helps keep your premiums stable and your coverage affordable. If you've had multiple issues recently, it might be smarter to handle a small repair out of pocket to protect your long-term rates.
Comprehensive vs. Collision: Why the Claim Type Matters
To understand if a glass claim impacts your wallet, you must know how insurers categorize the event. Most glass damage falls under comprehensive coverage. This specific coverage type protects against events that aren't the driver's fault. In contrast, collision coverage deals with accidents involving other cars or objects while you are driving. Understanding how auto insurance claims affect your premiums is essential because comprehensive claims are statistically less likely to trigger a rate surcharge. Insurers don't view a rock chip as proof of high-risk driving.
Because of this low-risk status, many providers actually incentivize windshield repair. They often waive the deductible entirely for minor chip repairs to avoid the higher cost of a full replacement. This proactive approach keeps your costs down and maintains your vehicle's safety. If you're still wondering, "does a glass claim raise my insurance rates," the answer typically depends on whether the claim stays in the comprehensive category.
What falls under Comprehensive Coverage?
Comprehensive coverage handles "acts of God" and other unpredictable damage. These incidents occur regardless of how safely you drive. Common examples include:
- Road Debris: Rock chips kicked up by gravel from other vehicles on the highway.
- Vandalism: Damage caused by someone breaking into the vehicle or intentional acts of mischief.
- Weather Events: Glass breakage caused by hail, falling tree branches, or extreme temperature shifts.
These are seen as random events. Because there's no driver error involved, your insurance company has little reason to increase your rates. They view these as maintenance events rather than liability risks.
When a Glass Claim becomes a Collision Claim
Not all glass damage is comprehensive. If your windshield breaks because you hit another vehicle or a stationary object like a fence or pole, it becomes a collision claim. In these scenarios, the insurer assigns fault to the driver. These are the specific types of claims that actually cause rates to rise because they suggest a higher probability of future accidents.
Accurate reporting is vital during the claims process to ensure the event is classified correctly. Navigating these definitions can be complex, but you don't have to do it alone. A professional provider can help verify your coverage details before work begins. If you need assistance with the process, you can consult with a glass specialist to discuss your options and ensure your claim is handled accurately.
Windshield Repair vs. Replacement: Impact on Policy Premiums
The specific type of service your vehicle needs plays a major role in how your insurance company handles the paperwork. Choosing between a simple fix and a full installation changes the total payout and the level of scrutiny your policy receives. If you're still asking, does a glass claim raise my insurance rates, the scale of the restoration is a key factor. Most insurers prefer the most cost-effective solution that restores your vehicle to a safe, roadworthy condition.
Insurers often view minor repairs as preventative maintenance. By fixing a small chip early, you prevent it from spreading into a large crack that requires a complete overhaul. This proactive approach saves the insurance company money and keeps your claims history relatively clean. When you opt for a repair over a replacement, you're choosing a path that is highly unlikely to trigger any negative adjustments to your premium.
The Incentive for Simple Repairs
Modern insurance policies often include a deductible waiver for windshield repairs. This means the insurer pays 100% of the cost, and you pay nothing out of pocket. It's a win-win scenario. You get a safe windshield without spending a dime, and the insurer avoids the much higher expense of a full replacement later. Fixing a chip quickly prevents the need for a future claim that could eventually impact your risk profile.
Standard industry practices favor these quick fixes. A typical repair takes less than 30 minutes and doesn't require complex parts. Because the cost is so low, it barely registers as a financial loss for the insurance company. Most providers don't count these minor repairs against you when calculating your renewal rates. They would rather encourage you to maintain your visibility and safety than penalize you for a small, no-fault incident.
The Rising Cost of Replacement and ADAS
When a windshield is too damaged to fix, the windshield replacement cost becomes a larger factor in the claim. Modern glass is no longer just a piece of transparent material. It's a complex component integrated with sensors, cameras, and heating elements. These technological advancements have increased the average payout for a glass claim, but they are essential for your vehicle's safety systems.
A critical part of this process is ADAS calibration auto glass. If your car has lane-keep assist, automatic emergency braking, or adaptive cruise control, the cameras behind the glass must be recalibrated after a replacement. Insurers recognize that this is a non-negotiable safety step. While it adds to the total claim value, it ensures your safety features function properly. Even with these higher costs, a single replacement claim for modern technology is still typically viewed as a comprehensive, no-fault event that won't hike your rates.
The Math Behind the Claim: When to Pay Out of Pocket
Filing a claim isn't always the most efficient financial choice. Even when the answer to does a glass claim raise my insurance rates is usually no, the math of your deductible might suggest a different path. You must weigh the immediate cost of the repair against your policy's structure. If you're constantly asking, does a glass claim raise my insurance rates, remember that keeping your claims history clean offers long-term benefits that often outweigh a small insurance payout today. Strategic drivers look at the total value of their policy over several years before making a move.
Every claim, even a no-fault one, remains on your record. Before you notify your provider, it's wise to understand the actual price of the service. You can get a professional quote from a specialist to see how it compares to your specific deductible. This clarity allows you to make a decision based on facts rather than fear. It ensures you don't use your insurance for a repair that you could have easily handled yourself.
The $500 Rule of Thumb
Many modern policies carry a $500 or $1,000 comprehensive deductible. If the cost of your glass is lower than this amount, involving your insurance company provides no benefit. For example, replacing a standard side window often costs less than a typical deductible. In these cases, paying cash is the smarter move. It keeps your record clear and saves you from the administrative hurdle of filing a formal report. You maintain your status as a low-risk policyholder while resolving the issue quickly.
Even if the repair cost is slightly above your deductible, consider the "zero-dollar" claim risk. Some insurers track the number of times you contact them, regardless of the payout. A high frequency of small claims can eventually lead to a higher risk profile. If the difference between your deductible and the total cost is minimal, paying out of pocket is often the better long-term strategy. This approach protects your standing with the insurance company for when you might face a much larger, more expensive claim later.
Factors to Consider Before Calling Your Agent
Your current policy's status is a major factor. Many insurers offer a "Claims-Free" discount that can save you significant money on your annual premium. Filing a glass claim might reset this discount, costing you more over the next few years than the repair itself. Always check if your discount is contingent on a completely empty claims history. Other factors include:
- Vehicle Age: Older vehicles may use standard aftermarket glass that is very affordable and doesn't require a claim.
- Glass Type: OEM glass for luxury vehicles is more expensive and usually justifies using your coverage.
- Recalibration: If your vehicle requires specialized safety system services, the total cost will likely exceed your deductible.
Understanding these variables helps you protect your insurance standing. Before making a final choice, review the Pinnacle Auto Glass professional solutions to see how modern technology affects your specific vehicle. Getting an expert opinion ensures you choose the most cost-effective path forward.
Navigating the Claims Process with Pinnacle Auto Glass
Dealing with insurance paperwork can feel overwhelming, especially when you're already concerned about vehicle damage. Many drivers hesitate to move forward because they aren't sure, does a glass claim raise my insurance rates? By choosing a partner that specializes in both technical installation and insurance coordination, you remove the guesswork from the equation. We verify your coverage and handle the communication with your provider directly to ensure the process remains transparent and stress-free. Our goal is to provide a seamless transition from a damaged windshield to a fully restored safety system.
Choosing a professional shop is the best way to protect your policy standing. We help you understand the specifics of your coverage before the work begins. This clarity prevents unexpected out-of-pocket costs and ensures the claim is filed correctly under your comprehensive benefits. When the paperwork is handled by experts, you can focus on getting back on the road safely.
Direct Insurance Billing and Support
We maintain professional relationships with major national insurance carriers to simplify your experience. This network allows us to streamline the verification of your benefits and coverage limits. Once you report the damage, our team takes over the administrative burden. We manage the direct billing process, which means you don't have to wait for reimbursement checks or navigate complex online portals. We focus on reducing the 'paperwork headache' for every vehicle owner we serve.
- Initial Assessment: We provide a clear quote and determine if the damage requires a repair or a full replacement.
- Coverage Verification: Our team contacts your insurer to confirm your deductible and policy details.
- Direct Billing: We submit the final invoice directly to the carrier, managing all the necessary documentation.
Ensuring Safety and Compliance
A windshield replacement is a critical restoration of your vehicle's structural integrity. The glass is a primary safety component that supports the roof during a rollover and ensures proper airbag deployment. For most vehicles manufactured after 2018, this process is not complete without ADAS recalibration. Because these safety systems are integrated into the glass, recalibration is mandatory to keep features like automatic emergency braking and lane-keep assist functioning correctly.
We handle these technical requirements in-house to ensure your vehicle remains compliant with manufacturer safety standards. This comprehensive approach protects your vehicle's resale value and ensures you aren't left with a secondary bill from a dealership. When you're weighing the question, does a glass claim raise my insurance rates, remember that insurers typically cover the full cost of recalibration because it prevents much more expensive accidents. Choosing a shop that provides these expert services ensures your vehicle is returned to you in peak condition, with all safety systems fully verified.
Protect Your Rates and Your Safety
Navigating auto insurance doesn't have to be a guessing game. Most drivers find that a single comprehensive claim for road debris won't impact their long-term costs. By understanding the no-fault nature of these incidents and comparing your deductible to the total repair cost, you can make a strategic choice for your wallet. You don't have to face the technical or administrative hurdles alone. Our team provides the clarity you need to move forward with confidence.
Pinnacle Auto Glass delivers the specialized expertise required for modern vehicle maintenance. We offer seamless insurance claim integration and include expert ADAS recalibration with our installations to ensure your safety systems remain compliant. Whether you require support for a personal vehicle or need professional solutions for national fleet and commercial support, we are ready to assist. Our specialists handle the technical details and the complexity of insurance paperwork simultaneously. This dual focus ensures your vehicle is safe and your claim is processed accurately. If you're still wondering, does a glass claim raise my insurance rates, the best first step is to get the facts about your specific damage.
Get a Professional Quote from Pinnacle Auto Glass Today and restore your peace of mind on the road. We look forward to helping you stay safe.
Frequently Asked Questions
Will my insurance premium go up if I file a claim for a rock chip?
No, your premium shouldn't increase for a simple rock chip repair. Most insurance providers view these small fixes as preventative maintenance. They would rather pay for a chip repair than a full windshield replacement later. Many policies even waive your deductible for repairs, meaning you pay nothing out of pocket. Because it's a no-fault event, it doesn't reflect your driving habits or increase your risk profile in the eyes of the insurer.
Does a glass claim count as an 'at-fault' accident?
A glass claim does not count as an at-fault accident. These incidents fall under comprehensive coverage, which handles damage from sources like road debris, weather, or vandalism. Since you didn't cause the damage through poor driving, the insurer doesn't penalize you for it. This is why the answer to does a glass claim raise my insurance rates is almost always no for an isolated incident involving standard road hazards.
Is it better to pay for a windshield replacement out of pocket?
It's better to pay out of pocket if the total cost is close to or less than your deductible. For example, if your deductible is $500 and the replacement costs $450, filing a claim offers no financial benefit. Paying cash keeps your claims history clean and preserves any "claims-free" discounts you currently enjoy. Always get a professional quote first to compare the actual price against your specific policy limits before deciding.
What happens if I have multiple glass claims in one year?
Frequent claims within a 12-month period can change how an insurer views your risk level. While one claim is usually fine, three or four in a single year might suggest you drive in high-risk areas. This pattern could lead to a premium increase or a higher deductible at renewal time. If you've already filed a claim recently, it's often wiser to handle minor glass issues out of pocket to protect your long-term standing.
Does insurance cover ADAS recalibration after a windshield replacement?
Insurance companies typically cover ADAS recalibration because it's a non-negotiable safety requirement. Modern vehicles use cameras and sensors mounted behind the windshield for features like automatic braking and lane-keep assist. These systems must be precisely calibrated after a replacement to function correctly. Since this is a manufacturer-mandated safety step, insurers include it in the total claim payout. Our team handles both the glass installation and the recalibration to ensure a seamless process.
Will my insurance company cancel my policy for a glass claim?
Your insurance company won't cancel your policy for a standard glass claim. Cancellation is a severe action usually reserved for non-payment, fraud, or a series of major at-fault accidents. A cracked windshield is a routine maintenance issue that insurers expect to handle. While multiple claims in a short time could impact your rates or deductible, a single comprehensive claim for glass is not a valid reason for an insurer to terminate your coverage.
Can I choose my own auto glass shop for an insurance claim?
You have the legal right to choose any auto glass shop you trust for your repair or replacement. While insurance agents often suggest a "preferred" provider, you aren't obligated to use them. It's important to select a shop that specializes in your specific vehicle's needs, including ADAS recalibration. We work directly with all major national carriers to manage the paperwork and billing, giving you the freedom to choose expert service without administrative stress.
How does a high deductible affect my choice to file a glass claim?
A high deductible often makes it impractical to file a claim for glass damage. If your deductible is $1,000, you'll likely pay the entire cost of the repair or replacement yourself. In this situation, the answer to does a glass claim raise my insurance rates becomes irrelevant because the insurer won't pay out any funds. It's smarter to pay the shop directly and avoid adding a "zero-dollar" claim to your permanent insurance record.


